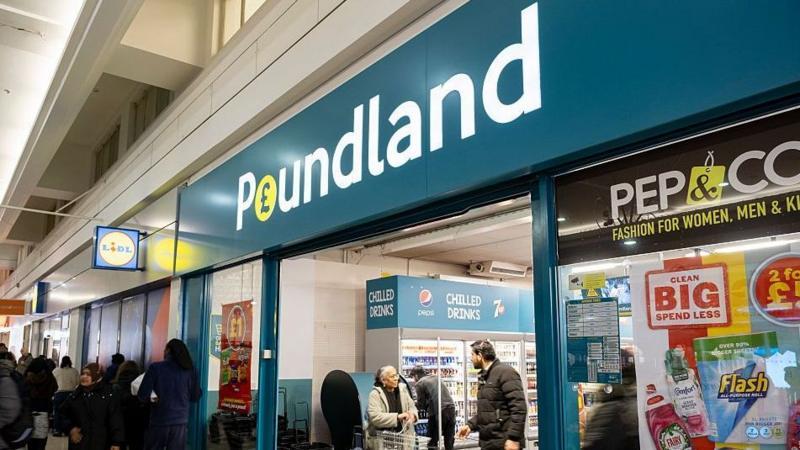
Poundland is facing imminent collapse after its American owner Gordon Brothers froze approximately £50m in the discount chain's bank accounts, preventing it from purchasing new stock to replenish its 600 stores. The retailer, which employs 11,000 staff, has until Thursday to secure a rescue deal and has filed a notice of intention to appoint administrators to protect itself from creditors during this critical window. According to BBC News, one insider described the business as "running on fumes" as shelves empty across the chain.
The funding freeze stems from a conflict between Gordon Brothers' dual position as both creditor and shareholder, though sources indicated they expected some relaxation of funds within two days. However, ITV News reported that management had been unable to access approximately £25m in cash as of 3 November, with suppliers left unpaid for new stock since 27 October when Gordon Brothers restricted access to cash and credit facilities.
Gordon Brothers, which acquired Poundland for £1 in June 2025, has faced mounting pressure after rejecting a takeover bid from Martin Property Group that could have preserved thousands of jobs. The owner has claimed it provided significant funding to support the company's trading since acquisition and has extracted £18m through debt interest payments and other fees and charges. However, Gordon Brothers has characterised the business as remaining "challenged and vulnerable to any potential downturn in future trading."
What do the latest financial figures show?
Poundland's chief executive Barry Williams told staff that like-for-like sales, which exclude new store openings, rose 11.4% in the week that included Halloween, exceeding budget by £1.5m. The business reported a profit of £18.1m in the year to September, representing what Williams described as a "strong recovery" from the previous year when it sustained losses of £68m. ITV reported an £86m turnaround in the company's fortunes, though the latest annual accounts have yet to be audited and could be revised upwards.
Who is attempting to rescue the business?
London-based Xyra Group has emerged as a leading contender in last-minute rescue efforts, with sources familiar with the sales process indicating the company is making "significant progress" and could now be the front runner. Xyra Group has proposed paying £12.5m immediately against a £30m loan, with the remaining balance deferred. Poundland co-founder Steve Smith has also signalled his willingness to invest in the business and attempted to contact Gordon Brothers about involvement in a rescue.
The rejected Martin Property Group offer reportedly failed to repay in full and immediately a £30m shareholder loan, a key obstacle that prevented that rescue from proceeding. An extension of Thursday's deadline now appears increasingly likely, though such an extension would be difficult to justify if Gordon Brothers continues to restrict funding. One observer noted that "if Gordon Brothers is going in front of that committee, you don't want to be giving the message we're pulling up the drawbridge."
What happens if no deal is reached?
If no solvent rescue materialises by Thursday, Poundland will collapse into administration and could be broken up. Even if a deal is agreed to sell the business as a whole, there is no guarantee a new owner would maintain all current store locations. However, suppliers to Poundland would prefer a scenario where the chain continues operating as a national entity rather than seeing hundreds of sites sold off piecemeal to other retailers.
Interest has been expressed by competitors including Poundstretcher, Tesco and B&M in acquiring individual stores, which could mean continued employment for many workers but under different ownership and branding. The central strategic question is whether a piecemeal sale would protect more jobs than a buyer willing to keep Poundland trading as a unified national chain.
What is happening in Parliament?
Gordon Brothers' executives are scheduled to appear before the Business Select Committee on Wednesday to face questioning from MPs about whether the owner is genuinely pursuing a solvent rescue and whether every realistic step is being taken to protect jobs and stores. The session is being held in private given that commercially sensitive discussions remain ongoing with multiple bidders. Business Minister Kate Dearden is expected to meet senior Poundland executives later in the week to discuss the threatened insolvency and government options.
Key Facts
- Poundland has 11,000 employees across 600 stores and faces a Thursday deadline to secure a rescue deal or enter administration
- Gordon Brothers froze approximately £50m in company funds, preventing restocking since 27 October
- Xyra Group is the leading rescue bidder, proposing to pay £12.5m immediately with remaining debt deferred
- The company reported £18.1m profit in the year to September, a turnaround from £68m losses the previous year
- A piecemeal sale to competitors could preserve some jobs but risks the loss of Poundland as a national chain