The UK state pension is on course to increase by 3.9% from April 2027, according to the latest wage growth data released today. Under the triple-lock mechanism, pensions rise annually by whichever is highest: average earnings growth, inflation, or a 2.5% floor. Today's figures showing total pay growth of 3.9% over the past year suggest this earnings measure will trigger the increase, unless September's inflation data reaches 4% or higher.
The government has previously confirmed that the state pension will continue to be protected by the triple lock, though calls persist from some quarters to suspend the policy. If the 3.9% rise is confirmed, the full new State Pension would climb to over £13,000 annually. According to government figures released in April 2026, the full new State Pension currently stands at £241.30 per week, or £12,547.60 per year, meaning a 3.9% increase would push it above the £13,000 threshold.
How will pensioners benefit from this rise?
For pensioners relying primarily on state pension income, another above-inflation increase represents welcome news and demonstrates the triple lock's effectiveness in preserving pension value over time. Jon Greer, head of retirement policy at Quilter, noted that
"If confirmed, this would see the full New State Pension rise to over £13,000. While we will need to wait for September's inflation figure before the uprating mechanism is formally confirmed, inflation is currently expected to remain below earnings growth, making an earnings-led increase the most likely outcome. For pensioners, another above-inflation increase will be welcome news and reflects the success of the triple lock in strengthening the value of the State Pension over time."
The state pension remains a foundational income source for millions of retirees and underpins many people's broader retirement planning. However, a significant complication looms: the rising pension will increasingly push recipients above the personal income tax allowance, creating a tax liability for some pensioners.
What is the tax problem facing pensioners?
As the state pension rises, more pensioners will find their income exceeding the personal income tax allowance, which remains frozen at £12,570 until April 2031. This frozen threshold, combined with rising pension payments, intensifies the squeeze on retirees whose sole income is the state pension. The government has pledged that pensioners whose only income is the state pension will not face tax bills in this Parliament, but critics argue the proposed solution is inadequate.
Money saving expert Martin Lewis reported receiving confirmation from pensions minister Torsten Bell that
"In line with the commitment made at Budget 2025, pensioners who only just exceed the personal allowance will not have the administrative burden of paying small amounts of tax in this Parliament. The chancellor will set out further details on how that commitment will be delivered at the Budget."
However, former Liberal Democrat pensions minister Sir Steve Webb has warned that the government's approach is
"a mess"and will protect only a small fraction of retirees. Webb, now a partner at consultants LCP, explained that
"Those on the new state pension can expect to see an increase of nearly £500 per year next April. But the sting in the tail is that this will take the standard rate of the new state pension above the tax threshold. The Government's plans to address this point are a mess, and likely to benefit only a small fraction of pensioners. They will also create unfairness between different groups of pensioners and between pensioners and low-paid workers, who do not qualify for any exemption."
Ian Futcher, financial planner at Quilter, highlighted the perverse incentive this creates:
"Someone relying solely on the State Pension will be protected from paying tax, while a pensioner who has built up even a relatively modest private pension could still find themselves facing a tax bill. After spending decades encouraging people to save for retirement, the system risks creating a cliff edge where those who have made additional provision can be treated less favourably than those relying entirely on the State Pension."
Will the triple lock debate reignite?
Today's earnings data is expected to rekindle political debate over the triple lock's sustainability. Susannah Streeter, chief investment strategist at Wealth Club, predicted that
"Pay growth is cooling, with regular earnings growth (including bonuses) easing to 3.9%, but that is hardly enough to make the inflation problem disappear. This snapshot points to a 3.9% rise in the state pension next April under the triple lock, with average earnings growth, the measure used for the calculation, being pushed higher by particularly strong public sector pay growth. Public sector pay is running at 6.3%, more than twice the 2.9% pace in the private sector, which reflects the impact of pay awards and the timing of them."
The controversy is likely to intensify given that government debt remains elevated and the cost of servicing it is substantial. Critics argue that using a pay measure inflated by public sector wage awards to drive up the state pension bill is problematic when the government faces pressure to contain spending and borrowing.

What about energy prices and household costs?
Pensioners and other households received some relief today as gas prices fell. The month-ahead UK gas price dropped 4% to 197.22p per therm, retreating from yesterday's highs when gas reached its highest level since December 2022. Energy prices had been climbing amid concerns over the lack of progress towards resolving the US-Iran conflict. However, household energy bills remain under pressure, with projections suggesting they could jump by approximately 25% in January based on recent wholesale energy price increases.
What does the jobs market reveal about economic weakness?
Today's employment figures mask significant underlying weakness in the labour market, according to multiple analysts. Mike Bell, head of market strategy for RBC BlueBay, warned that
"Today's UK jobs data is much weaker below the surface than the headline number suggests. The headline data is being hugely flattered by a surge in admin and support service and education jobs. The vast majority of private sectors are shedding jobs. The cumulative decline in employment from the peak in some sectors is becoming quite alarming. Also of concern is that employment in professional services and construction is now starting to decline along with the longstanding weakness in sectors like retail, hospitality, manufacturing and tech. The decline in employment is broad based across regions too."
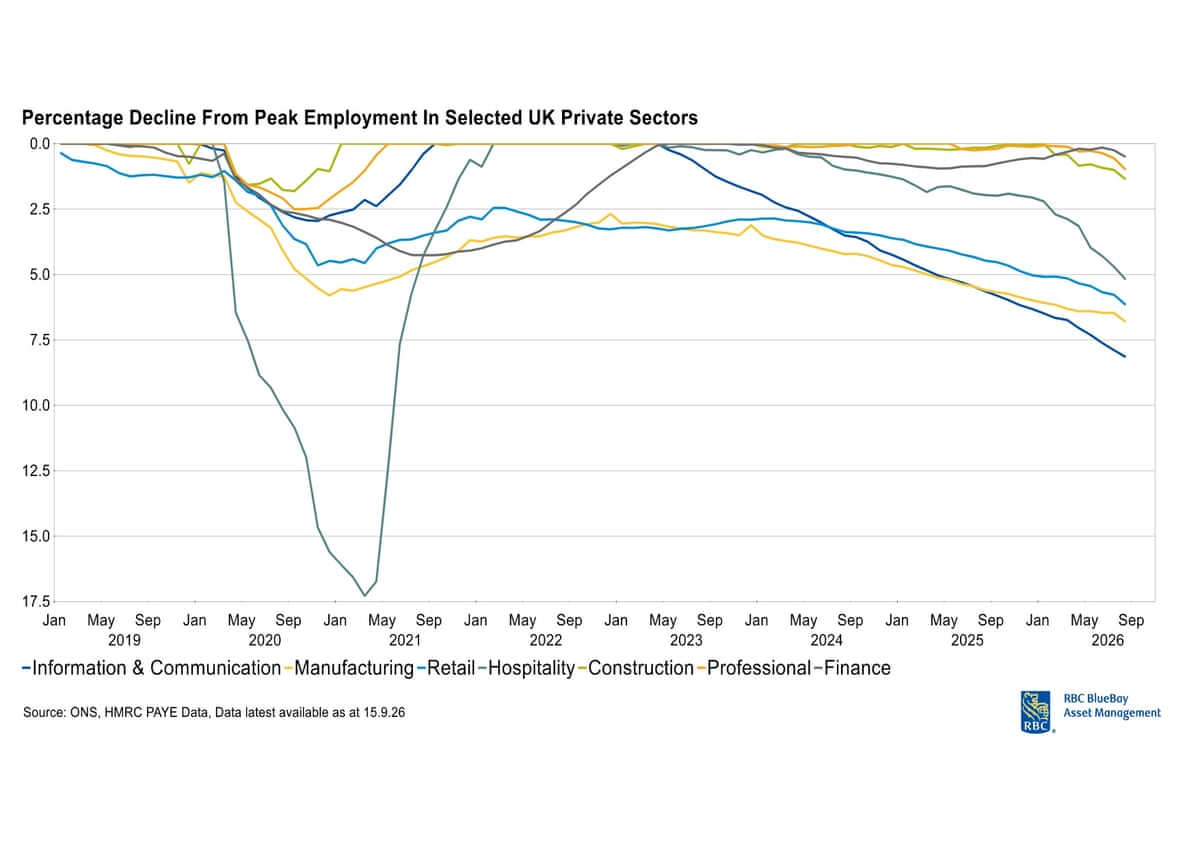
The retail and hospitality sectors continued to shed jobs over the summer. The British Retail Consortium calculated that retail employment has fallen by 122,000 positions over the past two years, limiting job opportunities for young people. Stephen Evans, chief executive at Learning and Work Institute, explained that
"Headline stability in the job stats masks two underlying and related challenges. The first is that one million young people are not in education, employment or training, risking long-term harm to their career prospects. Ramping up efforts to change that can't wait. The second is the stalling of job growth in parts of the private sectors like retail and hospitality, down 150,000 payroll jobs since last year. This limits first job opportunities for young people and reflects underlying economic weakness that ongoing international uncertainty won't help. The employment rate is relatively high by international standards, but risks trending in the wrong direction with 3.9 million people not in work but saying they want a job."
Suren Thiru, chief economist at the Institute of Chartered Accountants in England and Wales, warned that falling job vacancies signal weakening demand for workers:
"The ongoing drop in vacancies should set alarm bells ringing for the jobs market, as it suggests that demand for workers is wilting under the weight of soaring staffing costs, onerous regulation and increased automation. The UK labour market could be heading for a rockier autumn, as rising energy bills and pre-Budget tax uncertainty increasingly curb hiring intentions, resulting in moderately higher unemployment and lower pay growth."
How are financial markets reacting?
European stock markets declined this morning as investors grew anxious about the ongoing bond market sell-off and rising oil prices. Britain's FTSE 100 share index fell 90 points, or 0.85%, to 10,606 points. Germany's DAX and France's CAC 40 both dropped around 0.7%. Neil Wilson, investor strategist at Saxo UK, observed that
"Financials and miners are bearing the brunt in Europe, while AI stocks are down across Asia and the US."
The bond market sell-off has intensified, with US government bond yields breaking through 5% for the first time since 2023. The 10-year Treasury yield advanced to 5.03% this morning, reaching its highest level since 2007. Wilson noted that
"The US Treasury 10-year yield broke 5% for the first time since 2023 on Monday and advanced to a 19-year high as it touched 5.03% this morning...is this the point at which markets break? 5.25% is really when it gets dicey. Markets are pricing in a 93% chance the Fed hikes rates this week. While there are lots of reasons behind the bond rout, BMO says Treasury yields and oil prices haven't been this closely correlated for seven years."
UK bond yields have risen only slightly, potentially suppressed by reports that the Bank of England will halt its quantitative tightening programme—the sale of long-dated government bonds—later this week. That programme has been blamed for increasing bond supply in the market and pushing yields higher.
How are consumer spending patterns changing?
Families across Great Britain are tightening their belts in response to the cost of living crisis. Parents and carers spent 12.5% less on school uniforms in the four weeks to 6 September compared with the same period last year, turning to promotions and second-hand items to manage expenses. The average spend on school uniform fell to £54.53 from £62.29 year-on-year, according to market research company Worldpanel by Numerator.
Overall grocery inflation picked up to 2.3% from 2.1%, but consumer behaviour continues to shift. Branded goods outpaced supermarkets' own-label items for only the second time in the past year, with branded sales up 3.7% compared to 2.9% growth for own-label products. Despite this shift, shoppers maintained a strong appetite for promotions, with spending on grocery deals rising by £243 million, or 7% year-on-year, significantly outstripping full-price sales growth of just 1.4%.
Performance varied across major retailers. Marks & Spencer's grocery-only sales jumped 14.8% year-on-year. Asda returned to growth for the first time since March 2024, with sales up 0.1% over the 12 weeks to 6 September, though its market share dipped to 11.5%. The online grocer Ocado remained the fastest-growing retailer overall with sales up 13.3%, used by 4.4% of households. Lidl moved up to 8.7% market share from 8.3% a year ago, with sales rising 8%. Sainsbury's sales were 2.9% higher year-on-year, while Morrisons saw till spend rise 2.8%. Tesco, the UK's largest supermarket, saw sales rise 1.7% but market share dipped to 27.8% from 28.1%. Aldi's sales edged 0.7% higher, giving it a market share of 10.6%. The Co-op reported sales up 2.9% with market share flat at 5.5%, while Waitrose sales grew 2.8% with stable market share of 4.5%.
What happens next for state pension uprating?
The key data point determining the April 2027 state pension increase will be the Office for National Statistics earnings release, scheduled for 15 September 2026. September 2026 CPI inflation will be published later in October and will help determine whether earnings or prices set the next triple-lock rise. The triple lock mechanism uses the highest of September CPI inflation, May-to-July average earnings growth, or 2.5%, meaning the final uprating figure will not be formally confirmed until both data points are available.
Key Facts
- State pension is on course to rise 3.9% from April 2027 based on current wage growth data, potentially lifting the full new State Pension above £13,000 annually
- The frozen personal income tax allowance of £12,570 until April 2031 will increasingly push pensioners above the tax threshold, though the government has pledged to protect those relying solely on state pension income
- The labour market shows significant underlying weakness, with retail and hospitality shedding jobs and one million young people not in education, employment or training
- Consumer spending is under pressure, with families cutting back on school uniform costs by 12.5% and relying heavily on promotions and second-hand items
- Bond market sell-off has driven US 10-year Treasury yields to 5.03%, the highest since 2007, while UK yields remain relatively stable