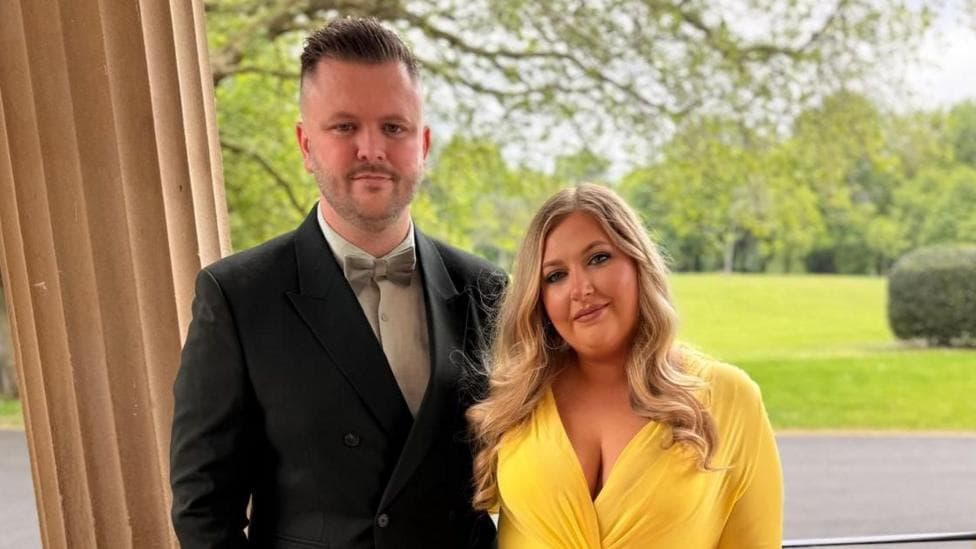
Until last year, Conroy, 32, and his partner Amber, 28, faced a seemingly insurmountable barrier to homeownership. Renting in central Manchester where both work, they struggled to accumulate sufficient savings for a property deposit. Their situation changed when they discovered a specialised mortgage product offering an unconventional path to ownership.
Skipton Building Society's Track Record mortgage finances the entire purchase price with no upfront payment required from the borrower. In August, Conroy and Amber purchased a four-bedroom property in Swinton, on Manchester's edge, for £242,000 using this product. They accepted a higher interest rate of 5.33% fixed for five years in exchange for avoiding a deposit requirement.
"I don't think it's dawned on us it's really ours,"says Conroy, who works as a video editor.
Why low-deposit mortgages are returning to the market
The resurgence of mortgages requiring minimal deposits marks a significant shift in lending practices. According to the Bank of England, the proportion of UK mortgages with deposits below 10% of the property value has reached its highest level since 2008, when such products were commonplace before the financial crisis. The typical first-time buyer deposit currently stands at approximately 20%, though this varies considerably by region—England averages £63,855 or 22% of purchase price, while Scottish buyers average £25,800 and London purchasers average £132,200.
Major lenders including Lloyds, Santander, Skipton and Yorkshire Building Society have introduced numerous mortgage products covering 95% to 100% of property values over recent years. These institutions argue they are addressing a genuine market need: as property prices climb and cost-of-living pressures make saving difficult, many capable borrowers remain locked out of homeownership. Skipton has positioned its Track Record mortgage as part of a broader effort to serve more prospective buyers, with borrowing limits reaching £600,000 and rates from 5.74% fixed for five years.
However, these products carry trade-offs. Interest rates are substantially higher than conventional mortgages, availability is restricted to specific property types and borrower profiles, and the risks warrant careful consideration.
Understanding the risks: negative equity and market downturns
The primary danger with zero or minimal-deposit mortgages is negative equity—a situation where the outstanding loan balance exceeds the property's market value. Should a borrower need to sell during a property market downturn, they could face significant financial losses.
Conroy acknowledges this risk explicitly. His 25-year loan carries monthly repayments of £1,500, roughly equivalent to his previous rent. He and Amber plan to make additional overpayments during the initial five-year fixed-rate period to build equity faster.
"There is always the element of a gamble with the property market,"he observes, though he has researched his local area and believes prices will not decline.
Similarly, Bronya, 27, and George, 29, purchased a four-bedroom house in Rhuddlan, North Wales in August using a low-deposit product from Lloyds. The lender advanced £258,000—approximately 98% of the property's value—over 33 years against a £5,000 deposit. At 5.89% fixed for five years, their monthly payments of £1,400 match their previous rent for a one-bedroom flat.

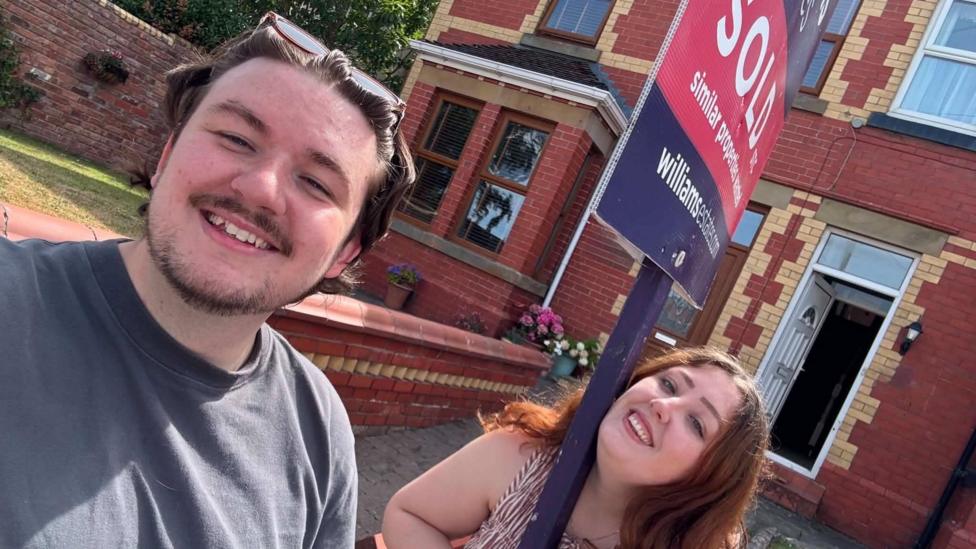
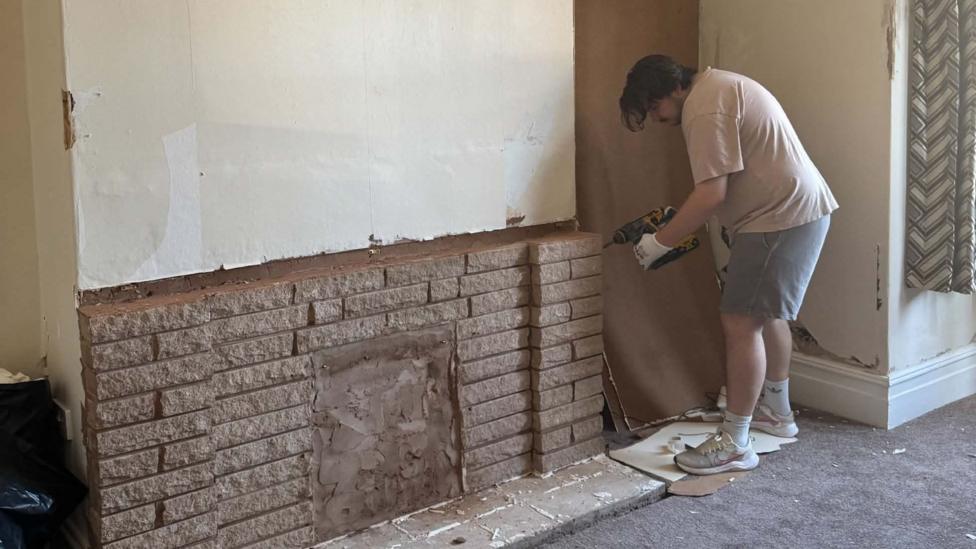
Bronya, employed as a civil servant, deliberately chose a minimal deposit to preserve savings for a renovation project exceeding £20,000. Both partners recognise the negative equity risk but believe their planned improvements will increase the home's value.
"We also plan to stay here our whole lives,"George explains, indicating their willingness to absorb any temporary market fluctuations.
How modern safeguards differ from 2008
The widespread availability of low-deposit mortgages to unqualified borrowers was identified as a critical factor in the 2008 global financial crisis. Today's products operate under substantially stricter conditions, according to David Hollingworth, associate director at mortgage brokers L&C Mortgages.
Skipton's Track Record applicants must demonstrate 12 consecutive months of rent payments and six months of on-time credit payments. The product is available only in England, Scotland and Wales, with borrowing capped at £600,000. Eligibility requires applicants to be at least 21 years old and not to have owned a property within the previous three years.
Lloyds imposes additional restrictions: its low-deposit mortgages are unavailable for new-build properties or shared ownership homes, limiting exposure to higher-risk segments.
Hollingworth notes that lenders increasingly recognise a distinction between affordability and deposit capacity.
"Lenders are recognising that some people have good affordability but may be struggling to save for a deposit while paying a rent and dealing with cost of living pressures."Recent regulatory changes have also permitted greater flexibility in lending multiples, provided borrowing remains within demonstrated means.
Nevertheless, Hollingworth urges prospective borrowers to exercise caution.
"Think carefully - what do monthly payments look like? Are you aware that interest rates could go up?"
The broader context for first-time buyers
The return of 100% mortgages reflects wider changes in the first-time buyer market. UK homebuyers currently face the highest mortgage affordability pressures since 2008, with significant regional disparities, according to recent industry reporting. Simultaneously, recent rule changes have enabled lenders to offer more flexible borrowing terms, potentially allowing first-time buyers to borrow up to six or seven times their income, though strict affordability criteria remain in place.
The market has widened considerably: as of September 2026, five UK lenders were offering genuine 100% loan-to-value mortgages, expanding beyond Skipton's specialist offering. This expansion suggests growing institutional confidence in the affordability checks and risk management frameworks now standard in the sector.
What happens next for borrowers
For Conroy and Amber, and for Bronya and George, the immediate focus is managing their fixed-rate periods. Skipton's Track Record product locks rates for five years, meaning the next significant decision point arrives when that term expires and borrowers must decide whether to remortgage. Both couples have demonstrated commitment to their purchases—through overpayment plans and renovation investments—suggesting they view these homes as long-term commitments rather than speculative acquisitions.
The broader question for the housing market is whether this expansion of low-deposit lending will prove sustainable or whether it represents a temporary response to affordability pressures. The experiences of borrowers like Conroy, Amber, Bronya and George will provide important evidence as the market evolves.